For banks, ag lenders & insurers
Know that the animal in your file is real, alive and where it’s supposed to be, so cattle can carry more of the collateral load.
Today, livestock is hard to verify
Lenders and insurers usually can’t confirm that a particular animal is the one they lent against or insured. Paper counts, inspections and producer statements leave room for “ghost” or “phantom” cows.
The result is that land carries the credit. Real estate is requested as collateral because it can be verified, and livestock alone often can’t.
Built around USDA animal disease traceability standards and designed to work with USDA-recognized official ear tags.
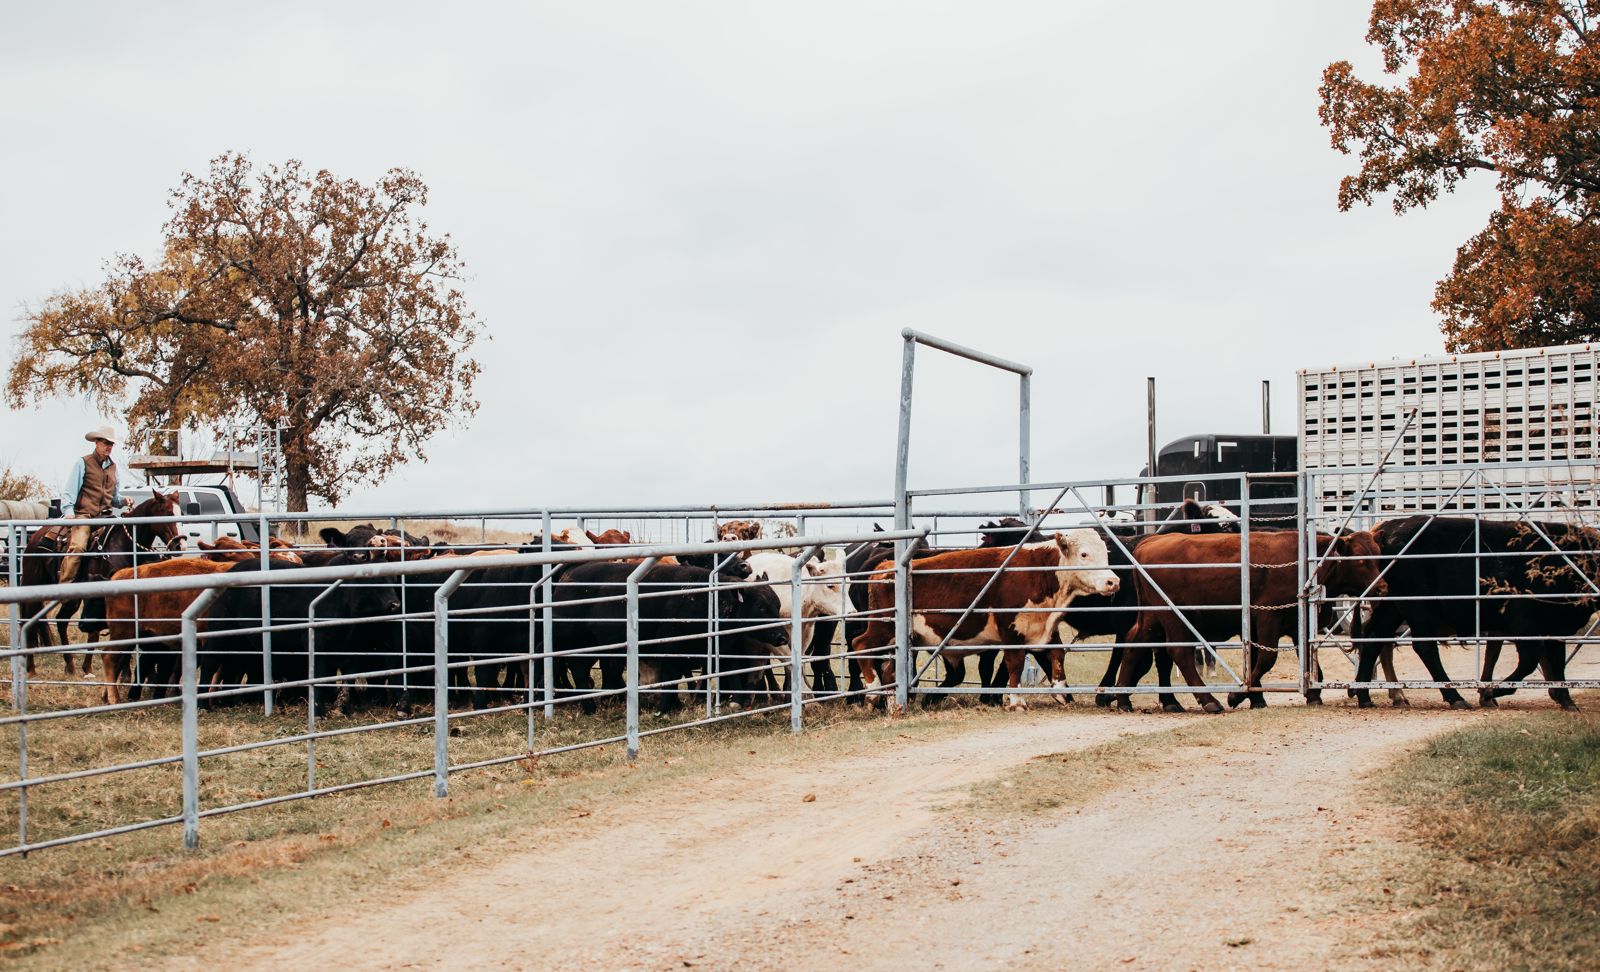
Tie the lien to a verified animal
- Per-animal electronic ID: AgOpen ID Tag plus rumen bolus
- Cryptographically signed records of identity, headcount, location and liveness
- A verification ledger of USDA-verified, U.S.-born-and-raised cattle
- Records designed so a UCC-1 can attach to a specific, verified animal
Built to support U.S.-born, raised, harvested and processed cattle records.
Where verified records help
Banks & ag lenders
Underwrite operating and livestock loans against verified animals, check collateral between inspections, and document the specific animals a UCC-1 covers. See it all at your desk in AgOpen Cattle Ledger and Cattle Books.
Insurers
Confirm that an insured animal exists and is alive, and keep a signed record of identity and location over the life of the policy.
Collateral monitoring
Follow headcount and liveness from signed records instead of relying only on periodic site visits.
Investors & counterparties
Give investors and other counterparties access to the same verified records the lender uses.
Prospective pilot lender
We are building the product alongside lenders and insurers. Pilot partners help decide which records matter, how they reach the loan file, and how verification fits current underwriting and lien practice.
Verified animals give underwriters better evidence, which is designed to support lower collateral risk and better loan terms for producers.
Note: AgOpen doesn’t provide legal, lending or insurance advice. How records are used in any lien or underwriting decision remains with each institution and its counsel.
Talk with us about a pilot